 James
Thirty-seven cents on the dollar. That’s roughly where a lot of first settlement offers land compared to what a claim eventually settles for, and the gap almost always hides inside one line item: pain and suffering. Nobody hands you a formula. Adjusters don’t publish their math. So most people guess, accept, and move on. Here’s what I want you to take from this piece: pain and suffering isn’t a mystery number pulled from thin air. It’s built from three inputs, and you can see all three if you know where to look. By the end, you’ll understand how a soft-tissue claim gets priced, why some crashes carry multiplier values above five, and what to gather in the first two weeks that changes the math in your favor.
What “pain and suffering” actually covers
Adjusters don’t use the phrase the way you do. In a claim file, it’s a bucket that holds physical pain, mental anguish, loss of enjoyment, scarring, and sometimes loss of consortium for a spouse. Your back hurts is one entry. You stopped coaching your kid’s soccer team is another, and it’s often worth more.
That second category is where most people leave money on the table. They describe symptoms. They don’t describe the life that disappeared. I’ve watched claimants write three pages about chiropractor visits and one sentence about quitting a hiking group they’d belonged to for nine years. The visits are documented. The hiking group is not, so the adjuster prices what’s in the file.
The two formulas adjusters actually run
Most adjusters start with the multiplier method. Take your hard economic damages, mostly medical bills and lost wages, and multiply by a number between 1.5 and 5. A clean fracture with a full recovery might sit at 1.5. A traumatic brain injury with permanent cognitive changes can push past 5, sometimes far past it. The multiplier isn’t random. It tracks how clearly your injury ties to the crash and how long the effects are expected to last.
The second method is per diem. The adjuster assigns a daily dollar figure to your pain and multiplies by the number of days you’re expected to suffer. A herniated disc that resolves in eight months at $100 a day lands near $24,000. The same injury with a surgeon saying “you’ll manage this for life” turns into a very different number. Which one gets used? Whichever produces the lower result, in my experience. That’s not cynicism; it’s just how the economics work on the other side of the table.
Why two identical crashes settle $80,000 apart
Picture two drivers rear-ended at the same intersection on the same afternoon. Both end up with a herniated disc at L4-L5. Same injury, same treatment plan, wildly different settlements. Here’s what separates them.
- Documentation density. One driver called the police, went to urgent care within six hours, and kept every appointment. The other waited four days, skipped two physical therapy sessions, and mentioned on Facebook that she was “feeling great today.” Guess which file looks weaker.
- Treatment gaps. A three-week gap between appointments reads as “probably healed.” Adjusters are trained to scan for gaps before they read anything else.
- Pre-existing conditions. If you had prior back issues, that doesn’t kill your claim, but it splits the causation argument. The adjuster will argue the crash aggravated something that was already there and price only the aggravation.
- Wage loss proof. Pay stubs and a letter from your employer beat a verbal estimate every time.
- The multiplier itself. This is where credibility enters. A claimant who exaggerates once gets priced as an exaggerator for the rest of the file.
According to the U.S. Census Bureau, millions of Americans change jobs or move every year, which matters more than it sounds: if you switch employers after a crash, your wage loss documentation gets harder to assemble, and that’s a real dollar cost. Keep your own copies of everything.
A three-lever framework you can use this week
I call it the three-lever model, and it’s the simplest way I know to think about your own claim before anyone else prices it.
- Lever one: severity proof. Objective findings beat subjective complaints. An MRI showing a disc bulge outperforms your description of the pain by a wide margin. If your doctor hasn’t ordered imaging and you’re still hurting after a few weeks, ask why.
- Lever two: duration proof. Every treatment note adds another brick to the wall. Consistency is the whole game. Same provider, same schedule, no gaps.
- Lever three: disruption proof. This is the lever people forget. Write down what you can’t do anymore. Specifics, dates, names. You used to lift weights four mornings a week. You haven’t since March. That’s a sentence an adjuster can price.
Pull all three levers hard, and the multiplier climbs. Miss one, and you’re negotiating from behind.
The evidence to collect in the first 14 days
The first two weeks set the ceiling for everything that follows. Here’s what to grab while it’s still available.
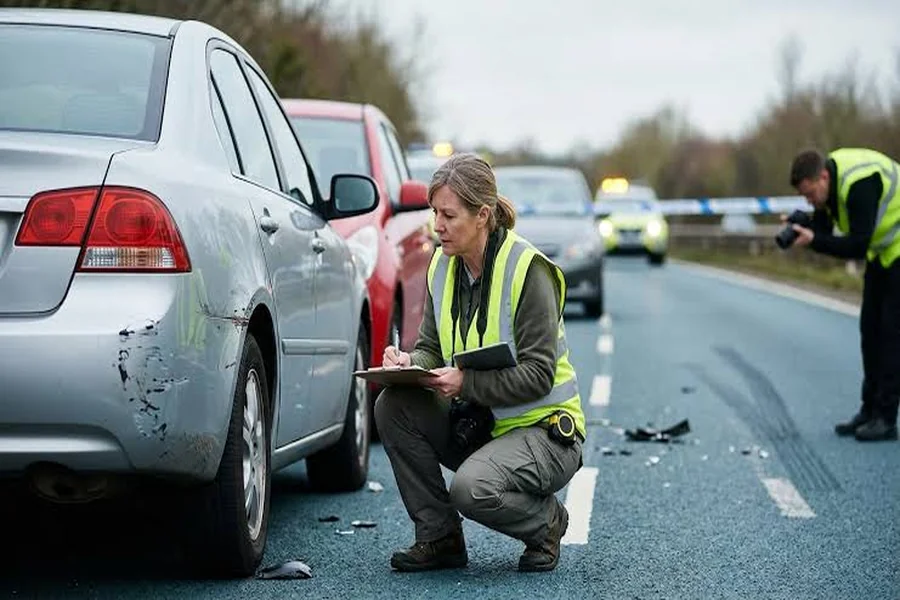
- Photographs. Vehicle damage from multiple angles, your visible injuries, and the scene if you can get back to it safely.
- The police report number. Not the report itself yet, just the number, so you can request it later without hunting.
- Medical records request forms. Sign them early so providers release records without a delay fight.
- A pain journal. Two lines a day. What hurt, what you skipped, how you slept.
- Witness names and numbers. Memories fade fast, and a neutral witness is worth real money in a disputed claim.
- Your own damage log. Every out-of-pocket expense: rideshares to appointments, prescriptions, ice packs, a brace.
Insurance is a heavily regulated industry, and the Insurance Information Institute tracks how the sector operates at a broad level, but no regulator will build your file for you. That part is on you, or on whoever you hire.
When a formula isn’t enough
Some claims outgrow the arithmetic. Permanent injuries, disputed liability, a commercial truck with a corporate defendant, or an insurer that simply won’t move off a lowball number. When that happens, the multiplier stops being a negotiating range and becomes something a jury might decide instead.
That’s usually the moment people start looking for a personal injury attorney. It’s a reasonable instinct. The Social Security Administration reports that a significant share of Americans rely on disability benefits at some point, which tells you how thin the safety net is when someone can’t work after an injury. A lawyer can front the cost of experts, take the case on contingency, and put the insurer on notice that the file has moved somewhere they can’t control.
Would I hire one for a minor fender bender with a full recovery? Honestly, no. The math doesn’t justify it. For a serious injury with long-term effects, the calculation flips hard, and it flips fast.
Questions people ask before they file
- Does the adjuster’s first offer mean anything? It means they want to close the file cheaply. It’s an opening position, not a valuation.
- Should I sign a medical release the insurer sends me? Read it closely. Broad releases let them pull your entire history, including records unrelated to the crash. Ask for a limited release instead.
- Can I negotiate without a lawyer? Yes, especially on clear-liability claims with modest injuries. Know your number before you call, and don’t accept the first, second, or third offer on the spot.
- How long do I have? Every state sets its own filing deadline, and it can be shorter than you expect. Ask a lawyer in your state rather than trusting a number you read online.
What to do with this
Pull out a notebook tonight and write down the three levers, then fill in what you actually have. If lever one is thin, call your doctor. If lever three is empty, start writing. The adjuster is going to price your claim whether you help or not, so you might as well hand them the strongest version of the story. Which of the three levers is weakest in your file right now?
